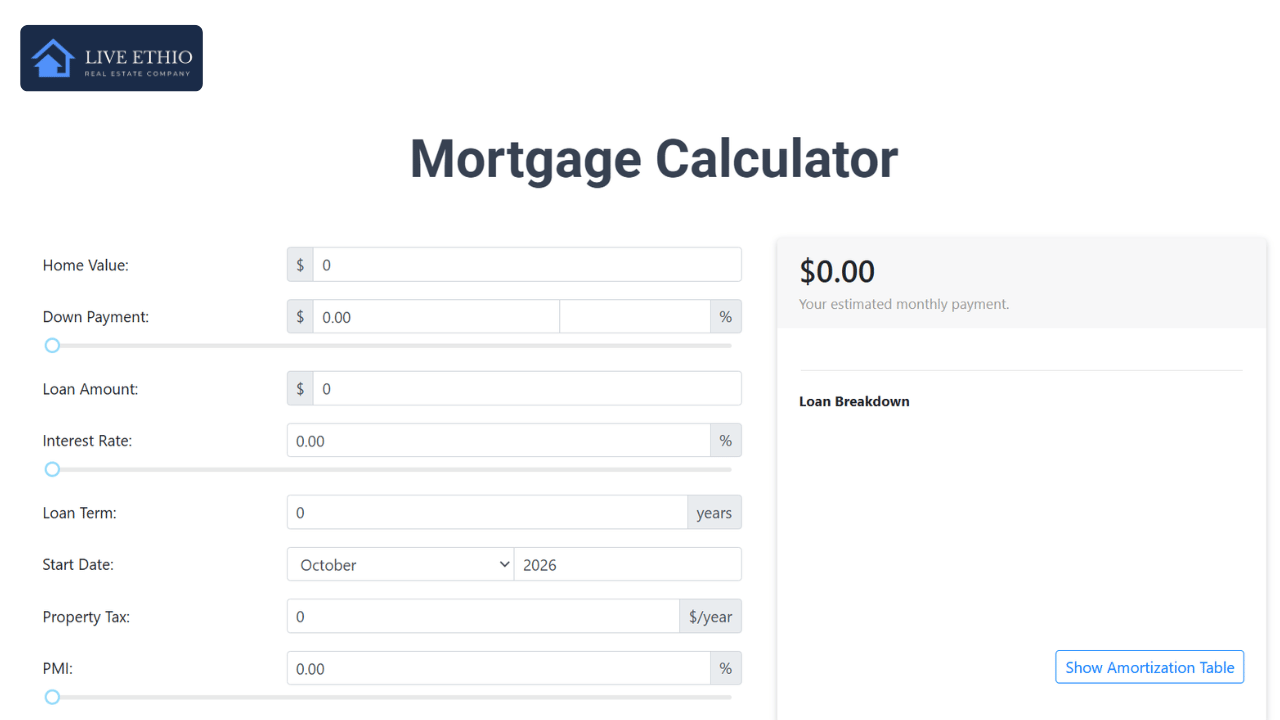
Buying a home in Ethiopia is a major financial decision, and for many buyers, paying the full purchase price upfront is not realistic. A mortgage can make homeownership more accessible by allowing buyers to pay for a property over several years, but understanding the monthly payment and total cost of the loan is essential before making a commitment. A mortgage calculator in Ethiopia can help you estimate how much you may need to pay each month based on the property's price, your down payment, the amount you borrow, the interest rate and the length of the loan. As Ethiopia's mortgage market continues to develop in 2026, understanding these numbers can help prospective buyers determine whether a property fits within their budget before they begin the application process.
How Does a Mortgage Work in Ethiopia?
A mortgage is a loan used to purchase residential property. Instead of paying the entire price of an apartment or house at once, a buyer provides an initial contribution, known as a down payment or equity contribution, and borrows the remaining amount from a financial institution. The borrower then repays the loan over an agreed period, usually through regular monthly payments. Each payment generally includes a portion that goes toward the outstanding principal and another portion that covers interest.The exact conditions vary between financial institutions. Interest rates, loan terms, required equity, eligibility requirements and other fees can all affect the final cost of borrowing. This is why buyers should compare the terms of available mortgage products rather than assuming that every bank offers the same financing conditions.
How to Use a Mortgage Calculator
A mortgage calculator requires a few basic numbers to estimate your monthly payment. The first is the property price. This is the purchase price of the apartment, house or other residential property you want to buy. Next is the down payment. This is the amount you contribute yourself before taking out the mortgage. For example, if a property costs 5 million ETB and you contribute 1 million ETB, you would need to finance the remaining 4 million ETB.
The loan amount is therefore the property price minus your down payment. You will also need the annual interest rate and the loan term, which is the number of years over which you plan to repay the mortgage. Once these figures are entered, the calculator can estimate your monthly payment and, depending on the calculator, the total amount you would repay over the life of the loan.
Mortgage Payment Example in Ethiopia
Let's look at a simple example.
Imagine you are considering an apartment priced at 5 million ETB and have saved 1 million ETB for the down payment.
Your estimated mortgage would therefore be:
Property price: 5,000,000 ETB
Down payment: 1,000,000 ETB
Loan amount: 4,000,000 ETB
If the loan carries an annual interest rate of 10% and is repaid over 20 years, the estimated monthly principal-and-interest payment would be approximately 38,600 ETB. Over the full 20-year period, the total amount paid toward principal and interest would be significantly higher than the original 4 million ETB loan because of the interest accumulated over time. This example is only an illustration. Actual mortgage payments can vary depending on the financial institution, the interest rate offered, the repayment structure, fees and the borrower's specific circumstances.
Why Interest Rates Matter So Much
One of the most important numbers in a mortgage calculation is the interest rate. Even a relatively small difference in the interest rate can make a significant difference when a large loan is repaid over many years. For example, a buyer borrowing several million birr may be able to manage a particular monthly payment at one interest rate but find the same property much less affordable if the rate is higher. This is particularly important in Ethiopia because mortgage interest rates are not necessarily identical across financial institutions. The National Bank of Ethiopia's 2026 interest-rate framework allows banks to determine lending rates based on market conditions and their own lending policies. As a result, buyers should use mortgage calculators to test different interest-rate scenarios rather than relying on a single rate when planning their budget.
How Much Down Payment Do You Need?
The required down payment depends on the mortgage product and the financial institution. Some mortgage products may finance a significant portion of a property's value, while others may require the buyer to provide a larger equity contribution. For example, the Commercial Bank of Ethiopia's stated diaspora mortgage product allows eligible borrowers to finance up to 80% of the residential property's cost, meaning the borrower provides at least 20% equity under that product's stated conditions. However, buyers should not assume that the same percentage applies to every mortgage product in Ethiopia. Requirements can vary based on the type of mortgage, the applicant's income and eligibility, the property and other factors. A larger down payment can also reduce the amount you need to borrow, which can lower your monthly payment and the total interest paid over the life of the loan.
How Long Should Your Mortgage Term Be?
The loan term is another important decision.
A longer mortgage term generally means lower monthly payments because the loan is spread over more years. However, you may pay considerably more interest over the entire repayment period.
A shorter loan term usually means higher monthly payments but less interest paid overall. For example, someone who can comfortably afford a higher monthly payment may prefer a shorter repayment period to reduce the total cost of borrowing. Another buyer may prefer a longer term because keeping monthly payments lower is more important for their household budget. The right choice depends on your income, existing financial commitments, savings and long-term plans.
What Income Do You Need to Qualify for a Mortgage?
There is no single income figure that guarantees mortgage approval in Ethiopia. Financial institutions typically consider factors such as the applicant's income, employment, existing debts, ability to repay the loan and the value of the property being financed. The relationship between your income and the proposed monthly payment is particularly important. A mortgage may technically be available for a certain property, but that does not necessarily mean the monthly payment is comfortable for your household. This is where using a mortgage calculator before applying can be useful. By testing different property prices, down payments and loan terms, you can establish a more realistic budget before you start looking at properties.
What Other Costs Should Home Buyers Consider?
Your mortgage payment is not necessarily the only cost involved in buying a property. Buyers should also consider expenses associated with purchasing and owning the property, which may include legal or administrative costs, property registration expenses, insurance, maintenance, service charges and other applicable fees. If you are purchasing an apartment in a managed building, there may also be monthly service or management charges. This means a buyer should avoid setting their entire housing budget based solely on the mortgage payment. A property with a monthly mortgage payment of 40,000 ETB, for example, may cost considerably more each month once other housing expenses are included.
Ethiopia's Mortgage Market Is Changing
The mortgage market in Ethiopia is also entering an important period of development. In 2026, the National Bank of Ethiopia introduced changes to the country's interest-rate framework, giving banks greater flexibility to determine lending rates. This means prospective borrowers need to pay attention to the specific mortgage product and terms offered by each financial institution rather than relying on a single market-wide mortgage rate. There has also been significant movement toward expanding mortgage financing. In September 2026, Ethiopia and the International Finance Corporation announced plans to establish the country's first dedicated mortgage refinance company, with proposed capital of 100 billion ETB. The initiative is intended to help expand access to mortgage financing and support the development of Ethiopia's housing finance market. If these efforts increase the availability of long-term housing finance, they could eventually give more buyers access to mortgages and contribute to the growth of Ethiopia's residential property market.
Is a Mortgage the Right Choice for You?
A mortgage can make it possible to purchase a property that would otherwise be unaffordable upfront, but taking on a long-term loan is a significant financial commitment. Before applying, consider whether the estimated monthly payment is manageable alongside your existing expenses. It is also worth considering whether your income is stable enough to support repayments over the full loan period. A useful approach is to calculate your expected payment using several different scenarios. Try a higher interest rate, a larger down payment and both shorter and longer repayment periods. This gives you a better understanding of how sensitive your budget is to changes in the loan terms. Most importantly, avoid choosing a property simply because you qualify for the maximum loan amount. The amount a bank is willing to lend and the amount you can comfortably afford are not always the same.
Frequently Asked Questions About Mortgages in Ethiopia
What is a mortgage calculator?
A mortgage calculator is a tool that estimates your monthly home-loan payment based on factors such as the loan amount, interest rate and repayment period. It can also help estimate the total amount you may repay over the life of the loan.
How much down payment do I need to buy a house in Ethiopia?
The required down payment varies depending on the financial institution, mortgage product and borrower. Some products may finance up to a certain percentage of the property's value, while others may require a larger equity contribution.
What interest rate can I expect on a mortgage in Ethiopia?
Mortgage interest rates vary between financial institutions and loan products. Ethiopia's 2026 interest-rate framework gives banks greater flexibility in determining lending rates, so buyers should check the current terms of the specific mortgage product they are considering.
Can I use a mortgage to buy an apartment in Addis Ababa?
Mortgage financing may be available for eligible buyers purchasing residential properties, including apartments, depending on the financial institution and mortgage product. Buyers should confirm the eligibility requirements and whether the specific property qualifies for financing.
Is a longer mortgage term better?
A longer loan term can reduce your monthly payment, but you will generally pay more interest over the life of the loan. A shorter term can reduce total interest but requires higher monthly payments.
How can I know how much house I can afford?
Start by calculating a realistic monthly housing budget based on your income, existing expenses, down payment and other financial commitments. Then use a mortgage calculator to compare different property prices, interest rates and loan terms before deciding how much you are comfortable borrowing.
Plan Your Home Purchase With Confidence
Buying property is a major financial decision, and understanding the numbers before you start searching can make the process much easier. A mortgage calculator can give you a starting point by showing how property price, down payment, interest rate and loan term affect your monthly payment. However, the result should be treated as an estimate rather than a guarantee of what a bank will offer. Once you have established a realistic budget, you can begin comparing properties that fit your financial situation. For buyers looking for apartments, houses and other residential properties in Addis Ababa, understanding your financing options can help you search more confidently and make a more informed purchasing decision.